OptionMetrics Launches IvyDB TradeFlow, Giving Institutions Insights on Buying and Selling Order Flow, Retail Trading Behavior, Participation in 0DTE Options Trading
New product gives quantitative professionals and academic researchers robust data and analytics on retail versus
Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.

OptionMetrics, the leading historical options data and analytics provider for institutional investors and academic researchers worldwide, today announced IvyDB TradeFlow to give quantitative professionals, options traders, and academic researchers an edge with data and analytics to classify retail versus institutional options trading and liquidity in today’s fast-moving markets.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20260930904765/en/
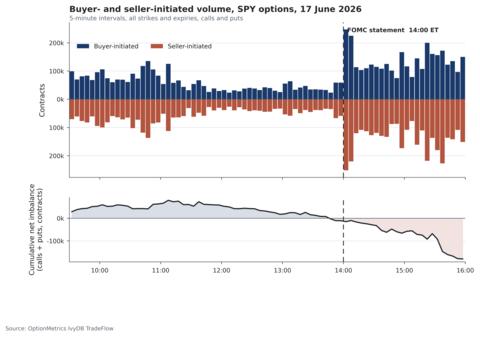
This chart illustrates total buyer- and seller-initiated trades of SPY options in 5-minute intervals on FOMC announcement day, with net imbalance defined as buyer-initiated minus seller-initiated volume. The chart indicates that heading into the 2:00pm ET release, the market broadly expected the Fed to hold its target rate. With the binary event resolved and no dovish shock to reprice, net options imbalance turned negative immediately after 2:00pm as traders sold contracts and unwound pre-announcement positions, representing post-event de-risking and volatility unwind. The chart was created with OptionMetrics’ IvyDB TradeFlow, which provides data and analytics on retail and institutional options trading and liquidity.
IvyDB TradeFlow is an evolution of OptionMetrics IvyDB Signed Volume and leverages a proprietary algorithm that delivers enhanced signaling and unmatched insights into order flow, participant activity, buy/sell pressure, and other critical analytics. It rapidly orders, classifies, and categorizes trade data from all U.S. exchanges, and sequentially processes data and analytics on retail and institutional investor trading at 5- and 30-minute, as well as end of day, intervals.
Designed to work alongside the gold standard in options data and analytics, IvyDB US, IvyDB TradeFlow tracks volume, buying and selling pressure, lot sizes, whether a trade occurred at the bid, ask, or midpoint for every option, every day since January 2016. It incorporates trade description codes and exchange venue data alongside Volume-Weighted Average Price (VWAP, or the average price a stock has traded at throughout the day) to more precisely assign directional volume and resolve midpoint trades. IvyDB TradeFlow also offers measures of trade aggressiveness relative to the SEC’s National Best Bid and Offer (NBBO) and proprietary indicators that identify and distinguish retail from institutional order flow.
“With the growing size and speed of today’s options market, and participation from retail investors, options activity can influence underlying stock prices, realized returns, and volatility. To evaluate strategies, Institutions need to understand how much is trading, who is driving activity and how aggressively they are positioning,” said Eran Steinberg, COO at OptionMetrics. “IvyDB TradeFlow offers a comprehensive view of trading across retail investors and market makers to identify shifts in positioning, liquidity and sentiment in rapidly changing markets.”
Contact OptionMetrics to learn more.
View source version on businesswire.com: https://www.businesswire.com/news/home/20260930904765/en/
Media gallery